.

Timothy G. Ventura

Chair, Philadelphia Professional Liability Practice Group

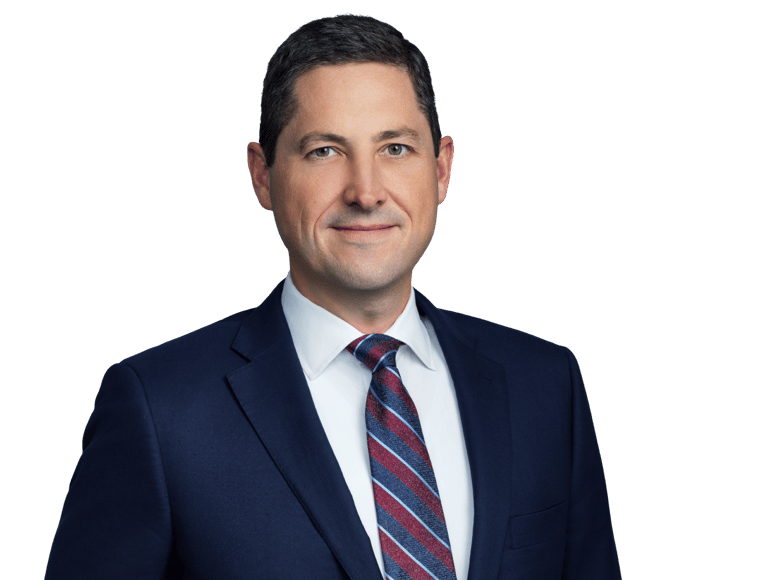
Portrait of Timothy G. Ventura

Tim is Chair of the Philadelphia Professional Liability Practice Group and the Insurance Agents and Brokers Liability Group. He focuses his practice on the defense of errors and omissions claims brought against insurance agents and brokers of all sizes. He also oversees and manages the day-to-day operations of a broad range of professional liability attorneys.  

While Tim’s practice is focused on defending insurance agents and brokers, he also frequently defends attorneys, corporate directors and officers, and a variety of real estate professionals, including title agents, appraisers, brokers, home inspectors and lenders in E&O and malpractice claims brought against them. He has successfully tried multiple cases as first chair counsel resulting in jury trial defense verdicts and tried dozens of arbitrations in Pennsylvania.  Tim also has experience defending product liability matters.

In addition to his civil litigation practice, Tim is a frequent speaker and author of publications on various topics regarding Insurance Agent/Broker Errors & Omissions, for clients, brokers, industry trade associations and professional liability insurers.

In 2003, Tim graduated from Boston College with a Bachelor of Arts in political science.  During the fall semester of his junior year at BC, he clerked for Senator John Kerry (D-MA).  Tim then attended Temple University Beasley School of Law in Philadelphia, PA, where he earned his juris doctor in 2006.  He achieved various honors while at Temple Law School, including: Temple University Law Faculty Scholarship recipient; Outstanding Oral Advocacy in Trial Advocacy; and Distinguished Classroom Performance – Civil Procedure.  He was also a staff member of the Temple Political and Civil Rights Law Review.

While attending Temple Law, Tim also worked part-time as a law clerk with Liberty Mutual Insurance Group in the Philadelphia Legal Department.

    • Temple University Beasley School of Law (J.D., 2006)
    • Boston College (B.A., 2003)
    • New Jersey, 2006
    • Pennsylvania, 2006
    • U.S. District Court Eastern District of Pennsylvania
    • U.S. District Court Middle District of Pennsylvania
    • American Bar Association
    • Claims and Litigation Management Alliance (CLM)
    • Pennsylvania Bar Association
    • Philadelphia Bar Association
    • Professional Liability Underwriting Society (PLUS)
    • The Seven-Ten Split Mock Trial: Navigating Agent Errors & Omissions, The Annual Professional Insurance Agents (PIA) Conference, Atlantic City, New Jersey, June 2, 2024
    • Pandemic Coverage Litigation Update / Insurance Broker Best Practices, Client Webinar, September 2022
    • The Aftermath of the Pandemic For Carriers and Agents, Client Webinar, July 2021
    • Pandemic Coverage Litigation Update - Agent E&O Wars to Come, Client Seminar, March 2021 
    • COVID 19 and Insurance Agent E&O, Best Practices, IA&B webinar, May 2020
    • Insurance Agent / Broker E&O Litigation Trends & Best Practices during COVID Crisis, Client Webinar, April 2020 
    • Insurance Agent / Broker E&O Litigation Trends & Best Practices, Client Seminar, April 2019
    • Insurance Agent / Broker E&O – Claims Prevention and Defense in 2018 and Beyond, Client webinar, February 2018
    • Mediation and Pre-Suit Claims Handling – Best Practices, Client Seminar, August 2016
    • Insurance Agent E&O Claims Prevention and Defense – The Road Ahead in 2016, Client Seminar, March 2016
    • Developments and Emerging Trends in the Legal and Insurance Areas of Cybersecurity, Client Seminar, February 2016
    • CPCU Society Webinar: Agent & Broker E&O - A New Lens for Viewing Exposures, September 18, 2015
    • Obtained a summary judgment dismissal in a Philadelphia Commerce Court commercial litigation matter. The case involved claims of unfair competition and tortious interference brought by one adult day care center against our client, a competing facility. The allegations centered on purported violations of regulations issued by the Pennsylvania Department of Aging and the Office of Long Term Living. The plaintiff’s final demand was $2 million, and no settlement offers were made before the trial court granted summary judgment.  
    • Obtained dismissal in Federal Court, Middle District of Pennsylvania, for insurance broker client in a case involving liability/commercial insurance coverage claims related to lost business income as a result of government mandated closures triggered by the COVID-19 pandemic.
    • Obtained summary judgment in Philadelphia County for our attorney/law firm client, dismissing a complex legal malpractice case involving claims of professional negligence and fraud that arose from an underlying personal injury litigation that concluded with a $700,000 settlement.  In the malpractice action, which involved various coverage and standard of care issues, Plaintiff sought approximately $2 million in damages.  Following discovery, the court granted our motion dismissing both the individual attorneys and firm clients with prejudice. For further details click here.
    • Obtained dismissal with prejudice of large automobile manufacturer client following motion oral argument. This case involved product liability claims regarding airbag deployment and alleged personal injuries caused by product defect.  No settlement offers made before suit was dismissed against client manufacturer. 
    • Defended insurance agency in Philadelphia Commerce Court action involving claims of professional negligence arising from the agency’s procurement of commercial insurance coverage for a hotel franchise owner.  Following a fire loss resulting in a completely rebuilt hotel property in Philadelphia, plaintiffs alleged their long-time insurance agency failed to obtain more comprehensive coverage available, including insufficient business interruption and ordinance or law coverage.  Plaintiffs also asserted breach of contract/bad faith claims against the insurer co-defendant.  With case exposure exceeding $8.5 million, following discovery and before trial, settled suit at mediation on behalf of insurance agency client with payment in the range of defense costs, a fraction of the total exposure and settlement demand.
    • Obtained jury trial defense verdict on behalf of large automobile manufacturer/distributor in Philadelphia County, Pennsylvania following four-day trial involving multiple party, fact witness and experts’ testimony.
    • Obtained jury trial defense verdict on behalf of product manufacturer in Lehigh County, Pennsylvania following three-day trial involving party, witness and multiple experts' testimony.
    • Obtained non-suit judgment for insurance broker at arbitration in Delaware County, Pennsylvania.
    • Obtained defense verdict for large automobile manufacturer at arbitration in Philadelphia County in a product liability suit involving fire cause and origin issues, with live expert testimony for both parties.
    • Obtained Non-Pros judgment in favor of wholesale insurance broker client in Philadelphia County, Pennsylvania.  After serving plaintiff's counsel with letters threatening sanctions and fees under Pa.R.C.P. 1023.1, and the prospect of a retaliatory suit against plaintiff's counsel for wrongful use of civil proceedings, because plaintiff's claims against the wholesale insurance broker lacked probable cause, plaintiff's counsel promptly withdrew representation and the suit languished resulting in a Non Pros judgment with no indemnity paid.
    • Obtained favorable outcome for large construction company client at private binding arbitration in a personal injury suit with a settlement demand of $600,000.  Following successful defense at arbitration, with multiple party and witness testimony and experts, the award resulted in client paying less than cost of trial defense.
    • Assisted first chair counsel in successful jury trial in Philadelphia County Court of Common Pleas.  Breach of contract/indemnity action representing construction manager against a sub-contractor, resulting in jury verdict recovery in excess of $750,000 on behalf of client.  Drafted successful pre-trial and post-trial motions, fact and expert witness coordination, with trial conference participation.
    • Obtained voluntary suit dismissal of plaintiff in legal malpractice suit with $2 million initial settlement demand after drafting successful Motion for Summary Judgment and procuring multiple defense expert reports on behalf of law firm and individual attorney clients.  Dispositive Motion established plaintiff's failure to prove her underlying case within the case and causation in professional negligence action, including the use of digital metadata analysis and litigation attorney expert opinion.
    • Defending for over ten years the manufacturer, designer and distributor of automobiles, motorcycles and varied power equipment in catastrophic injury, product liability and warranty actions.
    • Defending for over 8 years multiple wholesale and retail auto finance companies in commercial litigation and lender liability suits involving claims of fraud, breach of contract, professional negligence and unfair trade practices.

Results

Philadelphia Commerce Court Grants Summary Judgment, Dismissing $2M Unfair‑Competition and Tortious‑Interference Claims

We obtained summary judgment dismissal, following Oral Argument, in a Philadelphia Commerce Court commercial litigation matter involving allegations of unfair competition and tortious inference with contract and business relationships, brought by one adult day care center against our client, a competing adult day care facility.  The plaintiff’s suit stemmed from alleged violation of regulations set forth by the Pennsylvania Department of Aging and its Office of Long-Term Living. The plaintiff’s final demand was $2 million, and no settlement offers were made before the trial court granted summary judgment.

Montgomery County Court Dismisses Lawsuit Against Insurance Broker

We obtained dismissal of our insurance broker client on Motion for Summary Judgment in the Montgomery County Court of Common Pleas, Pennsylvania, on the basis of no duty breached, and lack of causation. Claimants asserted a professional negligence theory for allegedly allowing a commercial insurance policy to lapse, failing to notify the policyholder claimant of the lapse or cancellation, and allowing a subsequent gap in coverage to exist after the policy cancelled, when an underlying loss occurred. However, after completed discovery depositions and expert discovery, we successfully moved for summary judgment, arguing the policy cancelled because of the policyholder’s own failure to comply with premium audit requirements, rather than any liability or breach of standard of care by the insurance broker.

Thought Leadership

PLUS Blog

Insurance Broker Best Practices to Reduce AI-Related E&O Risk

August 25, 2026

Insurance agencies and brokerages, like most businesses, are increasingly using artificial intelligence and large language models (LLMs), such as ChatGPT and Gemini, in their daily operations. AI can provide significant advantages, including greater efficiency, enhanced productivity, and cost savings. For example, brokers may use AI to generate policy comparisons and proposals, accelerating the quoting process. However, these benefits come with risks. AI-generated information may be inaccurate, leading to improper advice, coverage misrepresentations, or binding coverage that violates underwriting guidelines. Overreliance on AI may also increase exposure to errors and omissions (E&O) claims and litigation. Insurance agencies can reduce AI-related risks by following these five best practices: 1. Require Licensed Producer Oversight AI can improve efficiency, but it does not replace the professional judgment or responsibility of a licensed producer. Treat AI-generated content as a preliminary draft that may contain errors. Before any quote, proposal, coverage summary, or policy comparison is provided to a client, a qualified individual should independently verify all material information, including coverage terms, limits, deductibles, exclusions and endorsements, against the applicable policy forms and source documents. 2. Establish a Formal AI Policy Agencies should adopt a written AI policy that defines: Approved AI tools; Information that may or may not be entered into AI platforms; AI outputs requiring licensed producer review; Tasks AI may assist with or perform autonomously, if any; and Permitted and prohibited uses. Approved uses may include document summarization and administrative support. Prohibited uses should include independently binding coverage, modifying limits, providing coverage advice, or communicating coverage determinations without human review. The policy should be distributed to all employees, supported by training, and reinforced through written acknowledgment of compliance. 3. Manage Third-Party AI and Data Security Risks Confidential client information, such as loss runs, financial records, proprietary information, or other sensitive data, should not be entered into unapproved public AI platforms. Agencies should also review contracts with AI vendors to ensure they adequately address confidentiality, cybersecurity controls, data retention, indemnification, insurance requirements, and limitations of liability. 4. Document AI Usage As with other client communications and insurance placement decisions, agencies should maintain records of AI-related activity. Documentation should reflect the client’s requests, information available to the producer, AI-generated output, any modifications or verification performed by agency personnel, communications with the client, and the coverage ultimately procured. Such records may provide valuable evidence in defending a future E&O claim. 5. Review Insurance Coverage Agencies should review their own E&O policies to determine whether any exclusions, limitations, or endorsements affect coverage for AI-related activities.  Likewise, agencies should be aware of any AI-related coverage restrictions contained in policies they recommend or place for clients. Conclusion AI is a valuable tool that can help insurance agents and brokers improve efficiency and service. However, it should supplement rather than replace the oversight, expertise, and professional judgment of a licensed producer. This article was originally published on PLUS Blog, the blog of the Professional Liability Underwriting Society, on August 20, 2026. All rights reserved. Further duplication without prior permission is prohibited. 

Defense Digest

On the Pulse…Defending the Professionals Who Power the Insurance Industry

March 1, 2026

The Insurance Agents and Brokers Defense Practice Group at Marshall Dennehey is nationally recognized for its skillful representation of insurance professionals in complex civil litigation. With decades of collective experience, our attorneys provide sophisticated, results-driven defense to insurance agents, brokers, managing general agents, and other intermediaries facing professional liability claims. We understand the intricate regulatory frameworks, contractual obligations, and industry standards that govern the insurance marketplace, allowing us to craft defenses that reflect both legal prowess and practical business insight. Our team regularly defends clients in claims alleging negligence, misrepresentation, breach of fiduciary duty, failure to procure coverage, and errors in policy placement or renewal. We also handle disputes arising from alleged bad faith, premium miscalculations, claims denial, and compliance violations. Whether the matter involves a single claim or a multi-jurisdictional class action, our attorneys have the depth of knowledge and trial experience necessary to protect our clients’ reputations and minimize their exposure. Beyond litigation, our practice group emphasizes proactive risk management and claim prevention. We partner with insurance agencies and brokerages to conduct internal audits, develop best practices, and deliver training on evolving industry risks, emerging coverage issues, and regulatory developments. This preventative approach reflects our broader commitment to supporting our clients as trusted advisors, not just defenders, throughout the life of their businesses. At Marshall Dennehey we understand that every claim against an insurance professional carries significant professional and reputational consequences. Our clients rely on us for strategic, efficient, and discreet representation that aligns with their long-term business goals. By combining deep industry knowledge with vigorous advocacy and an unwavering commitment to service, our Insurance Agents and Brokers Defense Practice Group stands at the forefront of protecting the professionals who keep the insurance industry moving. Tim is Chair of the Professional Liability Practice Group, and he can be reached at TGVentura@MDWCG.com.
Firm Highlights

Thought Leadership

The Search-Incident-to-Arrest Doctrine Does Not License Strip Searches

In Beatty v. Gardner, No. 25-2860 (3d Cir. Sept. 16, 2026), Kyle Beatty sued police officers Clinton Gardner and Calvin Irvin under 42 U.S.C. § 1983 after they stopped, arrested, and searched him three times during a drug investigation in Williamsport, Pennsylvania. The officers initially smelled marijuana coming from the car in which Beatty was sitting and observed marijuana residue, giving them probable cause to arrest him. Beatty consented to the first pat-down, and the second search was conducted incident to his lawful arrest; neither search uncovered weapons or contraband. The officers then transported Beatty to the police station solely to strip-search him, but the strip search also revealed nothing. The District Court granted the officers summary judgment, concluding that the initial stop, arrest, and first two searches were reasonable and that qualified immunity protected the officers from liability for the strip search. The Third Circuit affirmed, but held that the strip search itself violated the Fourth Amendment. The court concluded that the search-incident-to-arrest doctrine does not automatically permit officers to strip-search an arrestee outside the jail or prison setting. Because strip searches are highly intrusive and the traditional justifications for searches incident to arrest (officer safety and preservation of evidence) did not justify the search of Beatty, the officers generally needed either the arrestee’s consent, exigent circumstances, or a warrant supported by probable cause to believe that a search beneath the clothing would reveal weapons, contraband, or evidence. Here, the officers had none of those justifications. Nevertheless, the court held that qualified immunity barred damages liability because, at the time of the search, the right against a warrantless strip search of an arrestee outside the institutional setting was not clearly established by Supreme Court or Third Circuit precedent. The court likewise upheld qualified immunity on Beatty’s First Amendment retaliation claim and affirmed summary judgment for the officers.

Thought Leadership

Two Tracks, No Preclusion: Ohio Supreme Court Preserves Separate Damages Claims After Chapter 2506 Appeals

The Supreme Court of Ohio has clarified that an administrative appeal under Ohio Revised Code Chapter 2506 does not bar a separate action for damages and declaratory relief that could not have been pursued in the administrative appeal. The Ohio Supreme Court considered Sheetz, Inc. v. Centerville (2026-Ohio-3531) as a result of a certified question from the Southern District of Ohio. The question was whether Sheetz, the gas station/convenience store brand, was barred from seeking damages in a separate action since damages were not sought in their administrative appeal. Ultimately, the Ohio Supreme Court ruled that res judicata does not bar a separate action for damages after ruling on an administrative appeal because R.C. Chapter 2506 is limited to judicial review and cannot grant affirmative relief. The case arose after Centerville’s city council rejected a site plan proposed by Sheetz, Inc. that had received unanimous approval from the City’s planning commission. Sheetz filed an administrative appeal pursuant to R.C. 2506 in the Montgomery County Court of Common Pleas, and two months later filed a complaint for damages and declaratory relief under 42 USC § 1983 as a takings action with the city, city council, and other objectors as improper takings and a violation of due process, as well as interference with business and contractual relationship. The city and city council removed the § 1983 action for damages to federal court. Montgomery County Court of Common Pleas reversed the city council’s denial, and allowed the Sheetz project to move forward. Upon that ruling, the federal court issued a show-cause order questioning whether the § 1983 action was barred by the doctrine of res judicata via claim preclusion (which includes all theories of recovery).  Sheetz argued that Ohio courts of common pleas do not have authority to award damages or declaratory relief as party of the R.C. Ch. 2506 appeal, therefore res judicata could not be triggered to apply to the § 1983 action. Additionally, Sheetz moved to certify the issue to the Ohio Supreme Court, citing differing results between the second and sixth districts on this same issue. Centerville approached the question, not from a claim preclusion standpoint, but from the holding in Grava v. Parkman, Twp which states that a final judgment rendered on the merits bars all subsequent action based on the same transaction or occurrence.  In yet another approach, an objector argued that claim preclusion was satisfied because Sheetz could have raised its damages claims in the administrative appeal – Sheetz disagrees. In their analysis, the Supreme Court of Ohio broke down the elements of a claim preclusion analysis: 1) a prior final, valid decision on the merits by a court of competent jurisdiction; (2) a second action involving the same parties, or their privies, as the first; (3) a second action raising claims that were or could have been litigated in the first action; and (4) a second action arising out of the transaction or occurrence that was the subject matter of the previous action. The Court held that R.C. Ch. 2506 does not permit a party to argue damages as R.C. Ch. 2506 limits the common pleas jurisdiction as if it were sitting on appeal, and therefore can only affirm, reverse, vacate, or modify the appealed order, or can remand the case to the administrative body. Further, the Court held that Grava’s conclusion that a final judgment precludes additional litigation for different relief is inapplicable under this fact pattern because it was meant only to apply to those matters in which the plaintiff brings the exact same case twice, but for new relief. The Court found Grava was inapplicable because Sheetz could have requested damages or declaratory relief in the R.C. 2506 appeal. Therefore, Grava would be nothing more than dicta if it even did apply. Going further, the Ohio Supreme Court disavowed Sixth Circuit precedent which, in reliance on Grava and other district court decisions, permitted an owner to seeking relief under 42 U.S.C. § 1983 alongside an administrative appeal. See Moore v Hiram Twp., 988 F.3d 353 (6th Cir.2021). The Ohio Supreme Court found that the Sixth Circuit had disregarded a critical decision in Community Concerned Citizens, Inc. v. Union Twp. Bd. of Zoning Appeals, 1993-Ohio-115, which clearly held that a R.C. Ch. 2506 appeal cannot be combined with a complaint seeking other claims for relief. Id. at ¶ 11. To that end, the Ohio Supreme Court has determined that the decisions Moore relied on (outside of Grava) are no longer good law, and that Moore was wrongly decided. The decision draws a clear procedural boundary: Chapter 2506 provides judicial review of an administrative decision, not a forum for independent claims seeking affirmative relief. Although Grava may place claims arising from a single transaction within the potential scope of claim preclusion, those claims are not barred unless the complete claim-preclusion test is satisfied. Because Sheetz could not have pursued damages or declaratory relief in its Chapter 2506 appeal, the separate action was not precluded. The remaining question for practitioners looking to apply or defend against this exception is when does the statute of limitations begin to run on damages and declaratory relief claims related to an administrative decision on appeal? A takings action in federal court has a 2-year statute of limitations, or as a state claim, 4 years (like the other tortious claims raised therein). Correlating this case with others, an administrative appeal will not likely toll the statute of limitations on claims based on a final decision by a municipal authority. Therefore, practitioners should look for these cases to be brought simultaneously.

Thought Leadership

Pennsylvania Supreme Court to Review Whether Legal Malpractice Claims May Be Recast as Breach of Contract Claims

The Pennsylvania Supreme Court recently granted allowance of appeal to consider whether a plaintiff may pursue a breach of contract claim against an attorney based on allegations that the attorney failed to provide competent legal services. The issue is significant in professional liability litigation because it concerns whether a plaintiff may avoid the statute of limitations applicable to professional negligence claims by characterizing the alleged misconduct as a breach of contract. Antoine Poteat retained attorneys Gary Asteak and Nino V. Tinari to represent him in a criminal matter. After his conviction was subsequently overturned through a Post Conviction Relief Act proceeding, Poteat filed suit against his former attorneys alleging that they breached their retainer agreements by failing to provide competent legal services. The attorneys argued that the claims sounded in professional negligence, rather than breach of contract, and were therefore time-barred. The trial court dismissed Poteat’s complaint, but the Superior Court, sitting en banc, reversed. The Superior Court held that the gist-of-the-action doctrine did not bar Poteat’s breach of contract claim because the alleged failure to provide competent legal services could constitute a breach of the parties’ agreement. The Court further held that a legal-services agreement contains an implied duty requiring an attorney to provide competent legal services, even where the agreement does not contain an express provision requiring such services. The Pennsylvania Supreme Court granted review in July 2026 and will consider whether the Superior Court’s decision conflicts with Pennsylvania precedent distinguishing contract and tort claims, including Bruno v. Erie Insurance Co. The Supreme Court will also address whether a plaintiff may maintain a breach of contract claim based on an implied duty to provide competent legal services without identifying a specific contractual provision that was breached. The Supreme Court’s decision could have significant implications for professional liability litigation in Pennsylvania, particularly where plaintiffs seek to characterize claims arising from alleged professional negligence as contractual claims.