.

Patricia M. McDonagh

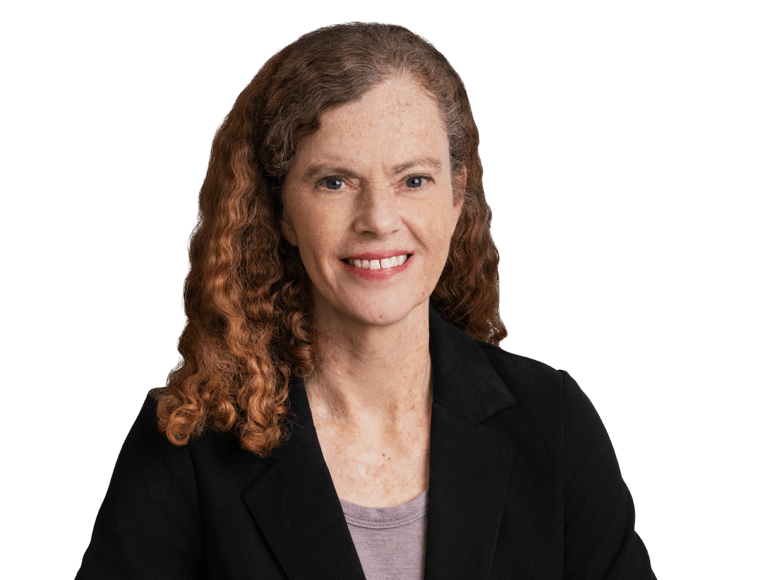
Portrait of Patricia M. McDonagh

Patricia concentrates her practice primarly on insurance coverage litigation and counseling, bad faith litigation, environmental and toxic tort litigation, and appellate practice. She has represented a large number of insurance companies and insurance industry professionals in both first and third party insurance coverage and bad faith matters. Patricia provides coverage opinions and advice to insurance carriers concerning their coverage obligations under insurance policies they issued and which provided CGL, homeowners', automobile liability, UM/UIM, PIP, workers' compensation and/or employer's liability coverage. She has also represented oil delivery companies and other third parties in litigation where they have been asked to assume or share in the costs of state-mandated clean up and remediation of environmental contamination. In addition, Patricia has had a great deal of experience in the defense of general liability, professional malpractice and products liability matters.

In 1990, Patricia graduated magna cum laude from Fairfield University. She then went on to obtain her juris doctor from Villanova University School of Law in 1993, after which she was admitted to the bar in the states of New Jersey and the Commonwealth of Pennsylvania.

After working for another defense litigation law firm in Morristown, New Jersey, Patricia joined Marshall Dennehey in 1997 and practices in the firm's Roseland, New Jersey, office, where she oversees the bad faith/coverage matters in that office.

    • Villanova University Charles Widger School of Law (J.D., 1993)
    • Fairfield University (B.A., magna cum laude, 1990)
    • New Jersey, 1993
    • The Best Lawyers in America©, Appellate Practice (2026-2027)
      • The Best Lawyers in America® list is published by Best Lawyers®. A description of the selection methodology can be found here. No aspect of this advertisement has been approved by the Supreme Court of New Jersey.
    • Essex County Bar Association
    • New Jersey State Bar Association
  • Assisted in securing a unanimous 6-0 defense verdict in a New Jersey premises liability case after the jury found no negligence on the part of the defendant. The plaintiff alleged that a six-foot drill bit fell from a retail display, causing a concussion, post-concussion syndrome and permanent cognitive impairments. The defense demonstrated that the item was displaced only after an unidentified customer struck the shelving with a shopping cart and that there was no evidence store employees knew or should have known of the condition. Through surveillance video, fact witness testimony and expert evidence, the defense also established that the impact was inconsistent with the forces necessary to cause a concussion and highlighted alternative explanations for the plaintiff's claimed injuries. Following a six-day trial, the jury returned a complete defense verdict, finding the defendant was not negligent.

    Secured a unanimous defense verdict in a premises liability matter involving a national home improvement retailer. The plaintiff alleged that she developed Complex Regional Pain Syndrome (CRPS) following a fall in the retailer's parking lot in October 2022. Plaintiff claimed that the incident necessitated significant ongoing medical treatment, including the implantation of a permanent spinal cord stimulator. The plaintiff sought substantial damages, including claims for extensive future medical care. The defense team successfully challenged the credibility of the plaintiff's allegations and expert testimony through rigorous cross-examination and the presentation of defense experts in forensic engineering, human factors, and pain management. The defense also demonstrated that the plaintiff's alleged condition was attributable to pre-existing medical issues rather than the incident at issue. Following a six-day trial, the jury deliberated for just 42 minutes before returning a unanimous verdict finding no negligence on the part of the defendant.

    Secured a no-cause verdict on behalf of a national home improvement retailer in a personal injury action. The plaintiff alleged that on May 20, 2019, she was injured at one of the retailer’s stores when an associate moved a lumber cart, causing a PVC pipe to fall and strike her head and right shoulder. She claimed permanent traumatic brain injury, concussion, and spinal injuries, supported by her orthopedic and neurologic experts. Our defense orthopedic and neurologic experts testified that the plaintiff’s reported symptoms were more consistent with malingering or a somatoform disorder. After a one-week trial and approximately 45 minutes of deliberation, the jury unanimously found the defendant was not negligent. The last demand was $1.2 million, and the final offer was $100,000.

    Obtained summary judgment in favor of an automobile liability insurance carrier, wherein court upheld carrier's disclaimer of defense and indemnity coverage to its insured in response to personal injury lawsuit brought against insured arising from motor vehicle accident on the basis that insured had made material misrepresentations on his insurance policy application as to where he resided and principally garaged the insured vehicle.

    Successfully represented an insurance carrier in a declaratory judgment action, wherein carrier disclaimed coverage to insured under an automobile liability insurance policy with regard to an underlying personal injury lawsuit brought against insured arising from a motor vehicle accident because insured failed to provide the carrier with notice of either the accident or the resultant lawsuit and which, in turn, substantially prejudiced the insurer.

    Obtained summary judgment on behalf of defendant employers and having all claims against them dismissed in civil lawsuits brought against them by their own employees for injuries the employees sustained in the workplace on the basis that there was no evidence to support a finding that the "intentional wrong" exception to the workers' compensation bar applied. In one of these cases, in particular, after successfully in having the plaintiff employee's claim against his employer dismissed, the employee continued to litigate his claim against the remaining defendant, a forklift manufacturer, resulting in a jury verdict in favor of the plaintiff in excess of $1 million, which was subsequently affirmed on appeal.

    Obtained summary judgment in favor of a commercial general liability carrier in a declaratory judgment action, successfully limiting the CGL carrier's potential liability exposure in a case involving serious injuries to two plaintiffs as a result of a robbery. Received a favorable ruling from the court that the $100,000 aggregate policy limit, set forth in the CGL policy's Assault & Battery Endorsement, was the applicable liability coverage limit potentially available to the injured plaintiffs under the CGL policy and not the $1 million per occurrence coverage limit, set forth in the policy's Declarations, as was argued by the plaintiffs.

    Successfully defended a CGL insurance carrier in a claim brought against it by the landlord/owner of a warehouse for defense and indemnity coverage as an Additional Insured under a CGL insurance policy issued by the carrier to one of the tenants at the warehouse in a high-exposure property damage loss case arising from a fire on the basis that the landlord did not qualify as an additional insured on the policy pursuant to the Additional Insured Endorsement and the landlord's claim should be a claim against its insurance broker for professional negligence in not procuring the proper insurance coverage requested by the landlord.

    Obtained summary judgment in favor of a subcontractor on an indemnity cross-claim, where the contract at issue, between the subcontractor and the general contractor, did not include the required express language that the general contractor would be indemnified for own negligence.

    • "New Jersey Supreme Court Holds that Evidence of an Insured’s Uncompensated Medical Expenses Falling Between the Insured’s Selected PIP Coverage and the Statutory Maximum PIP Coverage of $250,000 Is Inadmissible," Legal Updates for Coverage and Bad Faith, March 28, 2019
    • "New Jersey Environmental Insurance Law: The Battle Over Coverage Between Insurers and Policyholders, Arising from "Owned Property Exclusion" Clauses in CGL Policies," Defense Digest, Fall 2004
    • "Are E-Mails Privileged?," For The Defense, November 2000

Results

Summary Judgment for Insurer in Complex Coverage Case

We successfully persuaded the court to grant summary judgement on behalf of a major insurer on a complex coverage issue. This coverage case concerned two Virginia personal automobile policies in regard to an automobile accident in New Jersey. The son of a divorced couple sought coverage for an accident he was involved in on a major thoroughfare in New Jersey. At the time of the accident, the son was operating a motor vehicle owned by another Virginia resident, and he had the reasonable expectation that he had permission to operate the vehicle. The accident was very serious, and he sought coverage under both of his parents’ policies. As to the mother’s policy, we convinced the court that the son was not an insured under her policy because he was not so designated on the policy’s declaration page, which was a specific condition of the policy pursuant to Virginia law. As to the father’s policy, once again, we convinced the court that the son was not an insured under this policy given the fact that the mother had sole and exclusive custody under the divorce agreement; thus, the son was not a resident relative of the father’s household. Therefore, neither policy provided coverage for the son, and the insurer was totally dismissed from the case.

Court Agrees Mode of Operations Does Not Apply in Retail Liability Case

We were successful on a motion for summary judgment, thereby barring the application of the mode of operations in a slip and fall case where an alleged partially eaten sandwich was found in the aisle of the retailer. ​The facts indicated that the sandwich came from a fast-food sandwich shop within the premises and was dropped by an unidentified customer, who took the item to go and dropped it in the aisle before the plaintiff fell. The court ruled that the mode of operations did not apply because the aisle, which contained greeting cards and the like, and did not create an extension of the cafeteria within the retailer’s premises. Further, the court ruled there was no nexus to any self-serve component of the fast food restaurant’s business to the area in the retailer’s store proper where the accident occurred.

Firm Highlights

Thought Leadership

Commonwealth Court Reaffirms the Constitutionality of Act 111's IRE Provisions

In this case, the claimant sustained a work injury of January 6, 1994, which was acknowledged by Notice of Compensation Payable (NCP). After the claimant’s receipt of 104 weeks of temporary total disability benefits, the employer filed a Request for an Impairment Rating Examination (IRE). The IRE was performed in May 2023 and the IRE physician found that the claimant had a 5% whole person impairment, under the AMA Guides. The employer filed a Petition based on the IRE results, and the Petition was granted by the WCJ. During litigation, the claimant argued that the IRE provisions of Act 111 (Section 306(a.3) of the Act) were not applicable to her injury, since it predated June 24, 1996, the date Act 57 went into effect, and that the IRE provisions were unconstitutional. The Workers’ Compensation Judge (WCJ)) granted the Petition and the Board affirmed. On appeal to the Commonwealth Court, the claimant argued that Act 111 violated the nondelegation doctrine and that its retroactive application to the claimant’s injury was unconstitutional. The court rejected the arguments on the basis that they had already found the same arguments without merit in multiple, prior cases. The court also addressed an argument made by the claimant that Act 111 was procedurally defective under the Pennsylvania Constitution because it was only considered on two days in each House after having undergone amendments and reassignments. The court noted that the Pennsylvania Constitution requires every bill to be considered on three different days in each House. The claimant maintained that, according to the legislative history, the bill did not receive three separate days of consideration from each House when it was assigned a new bill number. The court pointed out, however, that the bill number, H.B. 1840 remained constant and was considered on three occasions by the House. Further, the court concluded that minor amendments to the bill were germane to its original subject, which was to modify the Act’s IRE process, in accordance with Protz II.

Thought Leadership

The Tolling Trap: Filing Alone Will Not Toll the Statute Without Good-Faith Service

The Eastern District of Pennsylvania recently reinforced a critical limitation on bad faith claims, holding that a timely filing alone will not preserve a cause of action absent a good-faith effort to serve the original process. The plaintiff had presented a claim for underinsured motorist benefits to his auto insurer. The insurer evaluated the claim and determined that the plaintiff’s accident-related damages did not exceed the bodily injury liability insurance limits of the at-fault driver and denied his claim. Among other claims, the plaintiff sought to present a claim for insurance bad faith under 42 Pa. C.S.A. § 8371, to which a two year statute of limitation applies. He first filed a praecipe for writ of summons before the expiration of the statute of limitation. However, the plaintiff did not attempt to serve the praecipe or writ until after the statute of limitations had expired. Additionally, the service failed as the plaintiff had mailed the original process to an incorrect address. Despite receipt of the Postal Service’s failure to deliver the original process, the plaintiff did not attempt to re-serve the writ. Two months later, the plaintiff filed a complaint and then successfully served that complaint. The insurer sought to dismiss the plaintiff’s bad faith claim as time-barred by the statute of limitations. The district court agreed. Though the plaintiff had filed a praecipe for a writ of summons prior to the expiration of the statute of limitations, the statute is only tolled if there is a good faith effort to serve that original process. In this case, the court determined that the plaintiff had failed to perform a “good faith effort to serve the original process”. Additionally, though the filing and service of a complaint can serve as alternative original process when the lawsuit is commenced by the filing of a praecipe for a writ of summons, the plaintiff filed his complaint after the statute of limitations had expired. The plaintiff’s bad faith claim was therefore determined to be barred by the statute of limitations and dismissed by the court, with prejudice. A key takeaway for the defense is not to assume that the statute of limitations has been successfully tolled by a plaintiff merely because a praecipe for a writ of summons or complaint has been filed prior to the expiration of the statute. A filed complaint or writ is only part of the equation. The defense should carefully review the docket and filings to confirm that the plaintiff also performed the requisite good faith effort to serve that original process. A thorough review of the docket may reveal that the plaintiff failed to make the good-faith service efforts necessary to toll the statute of limitations.

Thought Leadership

Florida Supreme Court Rules Florida Statute §627.70152 Does not Apply Retroactively

In a decision that resolves years of appellate uncertainty and confirms that insurers and insureds alike can rely on the legal framework in place when a policy is issued, the Supreme Court of Florida last week found that Florida Statute §627.70152, which involves an insured’s requirement to provide an insurer with pre-suit notice before filing a suit, cannot be applied retroactively. In Universal Property & Casualty Insurance Company v. Hughes, the Court was presented with the issue of whether the statutory pre-suit notice requirement applied retroactively and whether it would apply to a breach of contract of an insurance policy that was issued before the statute went into effect. Before the Court was an appeal from a homeowner, Ms. Hughes, who sued her insurance carrier, Universal Property & Casualty Insurance Company (Universal) for breach of contract under an insurance policy that was in effect from April 24, 2019 through April 24, 2020. During the policy period, Ms. Hughes suffered a loss and, on May 29, 2019, made a claim for water damage. The carrier investigated the loss and issued payment; Ms. Hughes disputed the payment, finding the amount insufficient for repairs. On July 1, 2021, Florida Statute §627.70152 went into effect, which required insureds to provide notice of intent to initiate litigation against the carrier prior to filing a lawsuit; if an insured filed the lawsuit without complying with §627.70152, a court must dismiss the case without prejudice. On August 4, 2021, Ms. Hughes filed her lawsuit against Universal for breach of contract. Universal moved to dismiss based on her failure to comply with §627.70152. Ms. Hughes contended the notice requirement could not be applied retroactively. The trial court disagreed and dismissed the lawsuit without prejudice, and Ms. Hughes appealed. During the appeal, the Fourth District Court of Appeal, in Cole v. Universal Property & Casualty, 363 So. 3d 1089 (Fla. 4th DCA 2023), ruled that Florida Statute §627.70152 did apply retroactively to policies issued before the effective date of §627.70152. However, the Sixth District Court agreed with Ms. Hughes and overturned the trial court’s ruling, finding the statute could not retroactively apply to policies issued prior to the statute effective date. Thereafter, the other district courts weighed in, with the Third District Court agreeing with the Fourth District Court, and the First, Second and Fifth District Courts agreeing with the Sixth District Court. In resolving the conflict amongst the district courts, the Supreme Court advised “as a general rule, ‘the statute in effect at the time an insurance contract is executed governs substantive issues arising in connection with that contract.’ Hassen v. State Farm Mut. Auto. Ins. Co., 674 So. 2d 106, 108 (Fla. 1996). The Court applied the two-step test when deciding whether a statute has retroactive application: “First, the Court must ascertain whether the Legislature intended for the statute to apply retroactively. Second, if such an intent is clearly expressed, the Court must determine whether retroactive application would violate any constitutional principles.” Menendez v. Progressive Exp. Ins. Co., 35 So. 3d 873, 877 (Fla. 2010). In analyzing the Legislature’s intent, the Court must determine whether the Legislature has manifested a clear command for retroactivity in the statutory text.  In review of the statutory text, the Court found nothing in the language of the statute to indicate that the phrase “all suits” was serving another purpose of expanding its reach to suits based on policies that both predate and postdate the enactment of the statute. Buis v. Universal Prop. & Cas. Ins. Co., 394 So. 3d 738, 741 (Fla. 2d DCA 2024). Further, the Court noted the statute has an effective date, which has long been considered to be evidence against retroactive application of a statute. The Court concluded that, on its face, no provision of §627.70152 speaks to application of the statute to insurance policies issued before the statute’s effective date and therefore, the Legislature did not clearly command retroactivity of the statute to include insurance policies issued prior to the enactment of the statute. The Court briefly reviewed Universal’s argument that the presuit notice requirement was procedural, not substantive, and therefore should be applied retroactively; however, the Court agreed with the Sixth District Court’s finding that, in its entirety, §627.70152 transformed an insured’s ability to sue an insurance company under a property insurance policy and an insurer’s obligations to respond to and pay insurance claims, thus making the requirement a substantive change. The Court thereby upheld the decision of the Sixth District and disapproved the decision of the Fourth District in Cole.