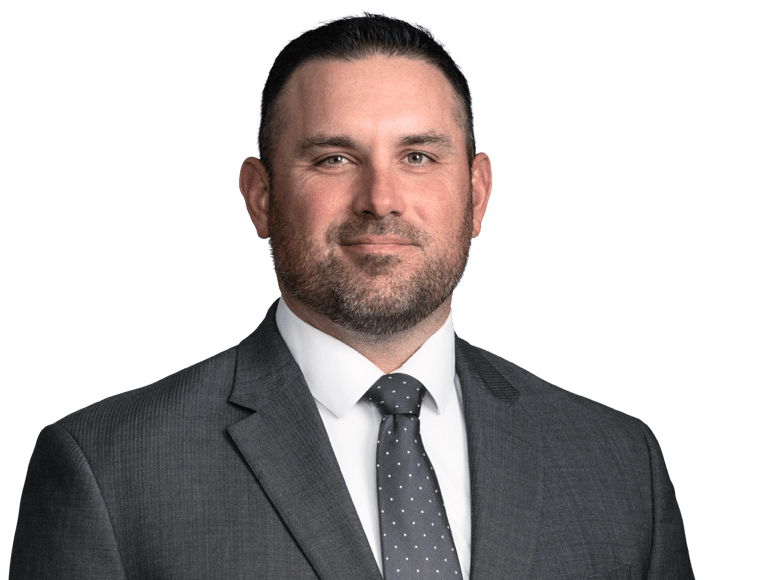
Matt is a shareholder in the firm's Fraud/Special Investigation Practice Group where he focuses primarily on large loss fraud and medical provider fraud. His practice in the area of fraud investigation involves the assessment and evaluation of both medical provider fraud and fraudulent claims on the part of his clients' insureds. Matt also has experience dealing with insurance coverage disputes, representing numerous insurance carriers across multiple states for the purposes of SIU investigation, bad faith litigation and general defense litigation. In doing so, Matt has represented a significant number of insurance carriers on these issues and has assisted in high-dollar and high-profile medical provider fraud, property loss and insurance fraud matters.
During his time with the firm, Matt has taken numerous Examinations Under Oath, drafted various complex coverage opinions and litigated topics of insurance fraud including, but not limited to, medical provider fraud, large loss property investigations and bad faith. In particular, he has assisted in multiple high-profile matters regarding carrier recovery of monies paid to fraudulent medical providers and as a result of fraudulent motor vehicle accidents. He has also successfully represented his clients in matters involving policy coverage and eligibility for benefits. Matt also has experience handling Personal Injury Protection (PIP) litigation, including matters involving coverage, benefits, and related disputes.
Matt earned his undergraduate degree from West Chester University and went on to receive his juris doctor from Widener University, in Wilmington, Delaware, graduating cum laude and with pro bono distinction. As a law student, he took part in Widener's Environmental Law Clinic, working with clients in all aspects of complex environmental litigation, and was the recipient of the Greenwatch Award for excellence in environmental law.
Prior to joining the firm, Matt represented insurance carriers and employers in the field of workers' compensation defense litigation where he handled matters in both Pennsylvania and New Jersey.
Thought Leadership
SIU Spotlight
Changes to NJ’s Open Public Records Act and Implications for SIU
March 1, 2025
In June 2024, New Jersey Governor Phil Murphy signed into law Senate Bill 2930, enacting significant amendments to New Jersey’s Open Public Records Act (OPRA). These changes, effective September 3, 2024, were made with the stated intent to modernize public records access, enhance transparency, and protect personal information. As access to public records is often a tool for SIU in investigating insurance claims, it will be important to understand the changes and how they may impact your investigation. The New Jersey Open Public Records Act, N.J.S.A. 47:1A-1 et. seq., was passed in 2002. It replaced New Jersey’s former Right to Know Law and also expanded the definition of a public record. The amendments passed late last year enacted changes to everything from the method to obtaining public records to which records can be provided and how. Some of the most relevant and important changes which should be noted by SIU follow. Attorney Fees Previously, requestors who were successful in court with respect to denied records requests were entitled to recover attorney’s fees. The new law limits the right to recover fees only upon a showing that the public agency “unreasonably denied access, acted in bad faith, or knowingly and willfully violated” OPRA. Further, if the records are provided within seven days of a lawsuit, attorney’s fees may be awarded only if the agency “knew or should have known” that the denial violated OPRA. Protective Orders Against Disruptive Requests Public agencies can now seek protective orders against individuals or entities whose records requests are intended to “substantially interrupt the performance of government function.” This was previously unavailable to public agencies. This potentially allows courts to issue orders to limit the scope or number of records requested. Public Records on Websites Agencies are now required to make records available on publicly accessible websites “to the extent feasible.” These websites must include a search function, and custodians must assist requestors in locating records online. This has the benefit of potentially streamlining the process of accessing public records, assuming the records are properly and fully placed online. Further, agencies may now be in compliance of specific records requests by directing the requestor to the online source provided they offer assistance in locating the records. Model Request Form There will now be a model request form that must be utilized by each public agency and used when requesting public records. The new model request form will include additional questions regarding commercial purpose, whether the records are being sought in connection with litigation, and the addition of new exemptions in the Exemptions Checklist section. Definition of “Commercial Purpose” The amendments introduce a new category of requestor—those seeking records for a “commercial purpose.” In addition to commercial entities, this category covers individuals who intend to use the records for the sale, solicitation, rent or lease or a service, or any use by which the user expects to profit either through commission, salary, or fee. Importantly for SIU, those requestors must certify that the records are for a commercial purpose and must provide the intended use of the records. The failure to do so can result in fines. Exemptions apply to journalists, educational institutions, and certain non-profits. The commercial purpose definition is not currently well defined and will likely be the subject of future litigation for clarification. Limitations on Use During Legal Proceedings The amendments to the OPRA law restricts parties to a legal proceeding from requesting records that are the subject of a court order, including pending discovery requests. Requestors must now certify whether their request is connected to a legal proceeding. In short, once litigation has been commenced, requestors will be foreclosed from seeking public records through the OPRA process. Notably, legal proceeding is not specifically defined in the statute, and this provision will apply regardless of whether the agency is a party to the proceeding or not. This is especially important for SIU. Requests for needed records or information important to your investigation must be made as early as possible and prior to any litigation being filed. Expanded Definition of Personal Identifying Information This definition now includes birth dates, personal email addresses, debit card and bank account information, home addresses, personal telephone numbers, personal information of juveniles under 18 (excepting MVC and elections information), HIPPA data, and indecent graphic images, all with the stated intent of enhancing the protection of personal data. Responses and Response Time Agencies must respond to proper requests, in writing, “as soon as possible but not later than seven (7) days after receipt of the request.” The response must address each item requested by either: granting access; denying access; seeking clarification of the request; or requesting an extension of time. Other Relevant Changes Identical Request: Agencies are no longer required to respond to identical requests for the same information from the same requestor if no information has changed. Appeal Timeframe: Requestors must appeal the denial of their request within 45 days. Records Kept by Others: Agencies are not obligated to respond to requests for records kept by separate public agencies. Vague Requests: Agencies are not required to respond to a request if it does not identify with specificity the information/documentation sought. Security Footage: Footage of public buildings is exempt unless the request identifies a specific incident that occurred, or a specified date and limited time period at a particular building. These amendments were enacted with the stated purpose of balancing the public’s right to access information with the need to protect personal privacy and prevent the misuse and abuse of the records request process. However, from a SIU perspective, the changes may have the effect of limiting access and transparency on the part of the agencies. It is crucial for the SIU community to familiarize itself with the new provisions to ensure compliance and maintain the ability to access public records necessary for effective and efficient claims investigations and determinations. SIU should take care to familiarize itself with the OPRA process and the new potential limitations and roadblocks to accessing public records. Additional care should be taken to ensure compliance with the updated processes and regulations when making records requests as well as the remedies available when encountered with failures to full comply or respond. *Matthew is a shareholder in our Mount Laurel, NJ office and a member of the Insurance Fraud/SIU Practice Group. (856) 414-6035 | MJBurdalski@mdwcg.com SIU Spotlight, Issue 2, Vol. 1, March 2025 is prepared by Marshall Dennehey to provide information on recent legal developments of interest to our readers. This publication is not intended to provide legal advice for a specific situation or to create an attorney-client relationship. We would be pleased to provide such legal assistance as you require on these and other subjects when called upon. ATTORNEY ADVERTISING pursuant to New York RPC 7.1 Copyright © 2025 Marshall Dennehey, all rights reserved. No part of this publication may be reprinted without the express written permission of our firm. For reprints or inquiries, or if you wish to be removed from this mailing list, contact tamontemuro@mdwcg.com.
SIU Spotlight
Class Action Out of Minnesota with Potential Impacts on Litigating and Negotiating Major Case
July 1, 2024
A class action suit is brewing in Minnesota which has the potential for major implications in the way major case investigations are litigated and negotiated. In Taqueria El Primo LLC et al. v. Illinois Farmers Ins. Co. et al., Civil No. 19-3071, the United States District Court for the District of Minnesota has certified a class action against Illinois Farms Insurance. The plaintiffs allege that so called “no-bill” or billing moratorium agreements between Farmers and certain medical providers are in violation of the Minnesota Deceptive Trade Practices Act, the Minnesota Consumer Fraud Act and the terms of the policy of insurance. the plaintiffs further allege that the billing limitations impacted have the potential to affect the ability of insureds to use PIP benefits under their policies to seek treatment with health care providers of their choice. Following SIU investigations revealing what Farmers believed to be fraudulent billing practices on the part of certain health care providers treating its insureds, Farmers entered into confidential settlement agreements with those health care providers in the state of Minnesota in which the providers agreed, in exchange for a settlement of Farmers’ claims, to not bill Farmers for treatment to its insureds. There were various such agreements with differing terms and conditions. The agreements, again with some exceptions, were also confidential per the terms and the settlements. Often, the confidentiality of the agreements was requested by the health care providers. The plaintiffs filed suit, alleging those non-disclosed agreements constituted unfair and illegal practices on the part of Farmers, resulting in the class members not receiving the value guaranteed by the policies of insurance purchased as they would not be able to use their No-Fault Benefits with any health care provider covered by such agreements. The plaintiffs are seeking monetary damages and injunctive relief voiding any such existing agreements. Farmers contends that the agreements were at all times legally permissible and has denied any and all violations of Minnesota law. Farmers argued that there was no proof at all from any class representative that medical treatment was sought and denied as a result of any no-bill agreement and that such agreements touched so small a percentage of available providers in the State there was no likelihood of any actual damage to any class member. The court ultimately approved the class action for monetary and injunctive relief on the Minnesota Consumer Fraud Act (MCFA) claim only. Regarding the breach of contract claim, the court agreed there had been no actual breach applicable to the class since there would need to be individualized evidence of a claim denied based on the at-issue agreements for the members of the Class. The Uniform Deceptive Trade Practices Act claim was similarly dismissed as there could be no theory of damages applicable to the class as a whole. Regarding the MCFA claim, the court allowed the same to go forward. The MCFA prohibits the “act, use or employment by any person of any fraud, false pretense, false promise, misrepresentation, misleading statement or deceptive practice, with the intent that others rely thereon in connection with the sale of any merchandise, whether or not any person has in fact been misled, deceived, or damaged thereby…” Minn. Stat. § 325F.69, subd. 1. In short, the court found that the MCFA claim could proceed since it is not necessary to show any individual consumer’s reliance on the purported wrongful conduct. All that is required is a causal nexus between the conduct and the damages of the plaintiffs established through direct or circumstantial evidence. The court found the case raises several common questions applicable to all class members: Whether the billing limitations violate the No-Fault Act; Whether the billing limitations violated the policies; Whether Farmers would have been able to sell the policies with the limitations at all; Whether Farmers would have been able to sell the policies only if it disclosed the limitations’ and Whether under Minnesota law it is inherently material and harmful to all purchasers as a matter of law, irrespective of individual consumer differences, if a company was only able to sell a product by fraudulently omitting a fact that if disclosed the company would have been barred from selling. The court likewise found that resolution of those questions posed several common questions of law which predominated over any differences between the class members. Finally, the court found that, if the plaintiffs’ theories were correct, damages could be measured on a class-wide basis, thus meeting the final elements necessary for class certification. The court did not engage in any discussion of the merits of the claims, but the very fact that the classes were certified and the legality of the no-bill agreements will now be litigated is a substantial development for the insurance community and SIU specifically. The failure to disclose the no-bill agreements to current and prospective insureds seems to have been the sticking point with the court. However, as previously noted, that confidentiality was bargained for by, in most cases, the health providers and their attorneys. No-bill agreements have been an important tool utilized by insures and SIU to effectively prevent further fraudulent billing by bad actor health care providers taking advantage of No-Fault benefits across the country. Such agreements arguably work to the benefit of insureds by preventing improper treatment and billing and keeping fraudulent actors at bay, resulting in reduced premiums. However, this current legal landscape puts those agreements directly at risk and should be followed closely. Matt is a shareholder in the firm’s Fraud/Special Investigation Practice Group where he focuses primarily on large loss fraud and medical provider fraud. His practice in the area of fraud investigation involves the assessment and evaluation of both medical provider fraud and fraudulent claims on the part of his clients’ insureds. SIU Spotlight, Issue 1, Vol. 1, July 2024 is prepared by Marshall Dennehey to provide information on recent legal developments of interest to our readers. This publication is not intended to provide legal advice for a specific situation or to create an attorney-client relationship. We would be pleased to provide such legal assistance as you require on these and other subjects when called upon. ATTORNEY ADVERTISING pursuant to New York RPC 7.1 Copyright © 2024 Marshall Dennehey, all rights reserved. No part of this publication may be reprinted without the express written permission of our firm. For reprints or inquiries, or if you wish to be removed from this mailing list, contact tamontemuro@mdwcg.com.