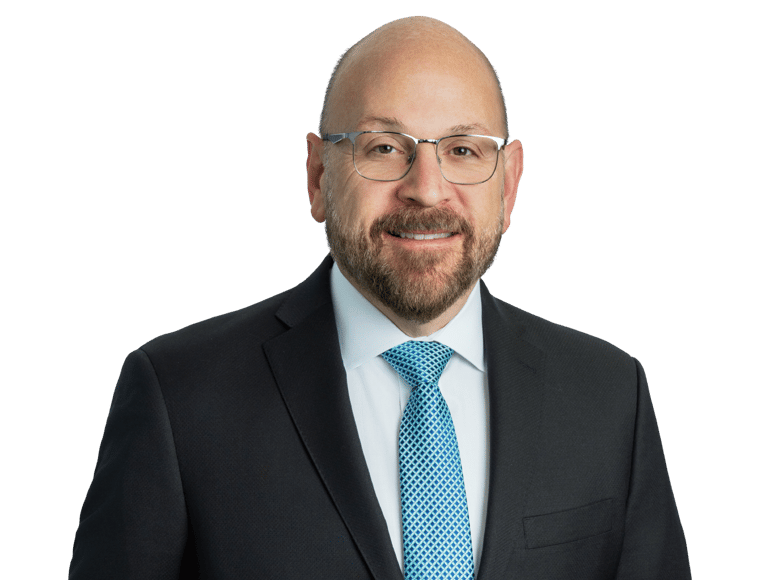
Gary Lesser is special counsel in the Casualty Department with extensive experience in disputes involving Personal Injury Protection claims and bodily injury claims. He also handles matters as a member of the Fraud/Special Investigation Practice Group. Gary primarily deals with evaluating both medical provider fraud and intentional/staged losses. In this arena, Gary has significant experience conducting Examinations Under Oath as it relates to both specific claims and broader SIU investigations.
Prior to joining Marshall Dennehey, Gary managed his own firm for almost 20 years where he handled bodily injury claims and PIP arbitrations on behalf of plaintiffs. Additionally, he was also a full time PIP Arbitrator for Forthright Solutions for almost 13 years hearing and deciding thousands of arbitrations between medical providers and automobile insurance carriers. Gary's unique perspective fosters a balanced understanding having represented both sides and enables him to approach legal matters with a comprehensive view and also develop effective strategies for each party.
Gary earned his juris doctor from the Cardozo School of Law and earned a B.A. in Political Science from Binghamton University.
He is admitted to practice in New Jersey and New York.
Thought Leadership
SIU Spotlight
Top 10 Recommendations for Addressing Fraud in NJ PIP Arbitration: A DRP’s Perspective
May 15, 2026
New Jersey’s no fault PIP system presents a unique blend of statutory requirements, arbitration procedures, and evolving fraud schemes. For carriers, counsel, and SIU professionals, navigating this landscape effectively requires more than familiarity with the rules — it demands an understanding of how Dispute Resolution Professionals (DRPs) evaluate evidence, credibility, and patterns of abuse. Drawing on more than a decade as a Forthright PIP arbitrator and extensive experience investigating staged losses and systemic fraud, I offer ten practical recommendations for strengthening fraud detection and improving outcomes in PIP arbitration. 1. Understand the NJ PIP Landscape New Jersey’s PIP framework is unlike any other. Arbitration, not Superior Court, is the primary forum for resolving disputes, and Forthright’s DRPs adjudicate cases based strictly on the evidence presented. Appreciating the procedural nuances — including timelines, evidentiary expectations, and the limits of DRP authority — is essential for building a defensible case. 2. Spot the Red Flags Early Fraud often reveals itself in the details. Early indicators include: Overutilization of treatment Templated or boilerplate medical reports Conflicting timelines Identical documentation across unrelated claimants Identifying these patterns at the outset allows carriers to intervene before questionable treatment escalates. 3. Investigate Policy Level Fraud Fraud doesn’t always begin with the accident. Policy level misrepresentations — such as false garaging locations, unlisted household residents, or misrepresented vehicle use — can undermine coverage entirely. Scrutinizing these issues early can support dismissal applications under the PIP rules. 4. Use the PIP Arbitration Rules to Your Advantage Rule 35 of the New Jersey No Fault PIP Arbitration Rules provides a mechanism for pre hearing dismissal when coverage requirements are not met. As the document notes: “If any party contends that… there is no coverage or Forthright lacks subject matter jurisdiction, such party may apply for an Order dismissing the case prior to hearing.” A well supported dismissal application — including policy provisions, factual support, and documentation — can resolve a dispute before it reaches a hearing. 5. Analyze Treatment Records for Patterns Fraud rarely occurs in isolation. Comparing CPT codes, treatment patterns, and provider behavior across multiple cases can reveal systemic issues. Reviewing prior arbitration awards involving the same providers can also uncover recurring credibility concerns or previously identified irregularities. 6. Use SIU Strategically SIU involvement is most effective when timed to coincide with treatment phases and targeted to specific concerns. Preparing SIU investigators with focused questions and clear objectives enhances credibility assessments and strengthens the evidentiary record. 7. Leverage the EUO Effectively Examinations Under Oath remain one of the most powerful tools in the investigative arsenal. Choosing between recorded statements and EUOs depends on timing and strategic goals. Records should be used to challenge inconsistencies in patient testimony and to test the reliability of the claimant’s narrative. 8. Prepare Your Arbitration Submission Thoughtfully A strong submission clearly identifies: The legal issues The evidence supporting your position How the facts align with your defense theory While written submissions are important, oral hearings often make the difference. DRPs value clarity, organization, and a well articulated argument. 9. Coach Your Witnesses Witness credibility can make or break a case. Preparing witnesses for cross examination ensures they present confidently and consistently. DRPs evaluate demeanor, clarity, and the ability to explain complex issues without overreaching. 10. Understand DRP Limitations — and Read Between the Lines DRPs decide cases based on the evidence presented, not investigative instincts. The civil burden of proof and limited credibility assessments shape outcomes. However, award language often contains subtle cues that can guide broader fraud detection efforts. Arbitration outcomes should be treated as investigative leads, not endpoints. Conclusion Fraud in New Jersey PIP claims continues to evolve, and carriers must adapt accordingly. By understanding the arbitration process, identifying red flags early, and presenting well supported cases, insurers can more effectively combat fraudulent activity while ensuring legitimate claimants receive the benefits they are entitled to. These ten recommendations reflect a DRP’s perspective — one grounded in thousands of cases, systemic investigations, and a deep understanding of how fraud manifests in the PIP environment. With thoughtful preparation and strategic execution, carriers can significantly improve their ability to detect, challenge, and prevent fraudulent claims.
SIU Spotlight
Is the Operator of a Low-Speed Electric Scooter a “Pedestrian” Under N.J.S.A. 39:6a-2(H) and Entitled to PIP Benefits?
July 1, 2024
By way of background, on November 22, 2021, David Goyco was operating a Segway low-speed electric scooter (LSES), which has a maximum speed of 15.5 miles per hour, when he was struck by an automobile. As a result of the collision, Goyco sustained bodily injuries and incurred expenses associated with his medical treatment. At the time of the accident, Goyco was insured under a policy of automobile insurance issued by Progressive Insurance Company. Goyco filed a claim for PIP benefits with Progressive Insurance Company. Progressive denied the claim stating that the LSES that Goyco was operating at the time of the accident did not meet the definition of a qualifying automobile pursuant to N.J.A.C. 39:6A-2(a) of the New Jersey Auto Insurance Law. Progressive further denied Goyco’s claim for PIP benefits arguing that the LSES that was being operated at the time of the accident does not qualify him for meeting the definition of a pedestrian. Pedestrian is defined as “[a]ny person who is not occupying, entering into, or alighting from a vehicle propelled by other that muscular power and designed primarily for use on highways, rails and tracks.” N.J.A.C. 39:6A-2(h). In New Jersey, motorized scooters are generally categories as the same as motorcycles. As such, they are not subject to the statutory PIP benefits. See, Gerber v. Allstate Ins. Co., 161 N.J.Super. 543, 391 A.2d 1285 (Law Div.), holding that a motor scooter is a motorcycle. See also, Muto v. Kemper Reinsurance Co., 189 N.J.Super. 417 (App. Div. 1983), holding that motorcycle does not fall within the definition of an automobile. However, a person not using a motorized or self propelled bicycle fits the definition of a “pedestrian” for the purposes of pedestrian PIP. See, Harbold v. Olin, 287 N.J.Super, 35 (App. Div. 1996), where it was found that, “[a] person riding a bicycle is considered a pedestrian for purposes of [New Jersey] automobile insurance laws. See also, Nuang by Nuang v. Pennsylvania Nat. Mut. Cas. Ins. Co., 224 N.J.Super. 753, 758, 541 A.2d 306, 308 (App. Div. 1988), holding that mopeds are always to be considered vehicles propelled by other than muscular power. On May 13, 2019, Governor Murphy issued a press release explaining that Bill S731 (N.J.S.A. 39:4-14.16(g) was passed so that “motorized scooters and e-bikes capable of traveling 20 miles per hour or slower [could] be regulated much the same as ordinary bicycles, allowing their operation on streets, highways, and bicycle paths in this State.” It was further explained that such bicycles and scooters will not require registration, insurance, or a driver’s license. Moreover, it was explained that “[t]he bill further provides that all statutes, rules and regulations that apply to ordinary bicycles will apply to low-speed electric bicycles and motorized scooters.” Goyco filed a lawsuit in Superior Court challenging Progressive’s denial of his claim. He argued that New Jersey law does recognize bicyclists as pedestrians for purpose of PIP coverage, and by extension, a LSES should be considered the equivalent of a bicycle pursuant to N.J.S.A. 39:4-14.16(g). The trial court dismissed Goyco’s complaint saying that the plaintiff was operating a scooter powered by motor at the time of the incident. As the scooter is clearly not considered a motor vehicle, neither in statute nor in the insurance policy, it must be determined if plaintiff would be considered a pedestrian. The trial court further found the plaintiff’s reliance on N.J.S.A. 39:4-14.16(g) is misplaced as the Statute is not a part of the No-Fault statute and is not controlling over the New Jersey Auto Insurance Law. Moreover, the trial court found that the definition of pedestrian in N.J.S.A 39:6A-4 “clearly has no application to an LSES either...[t]he LSES was not muscular powered thus does not meet the requirements of the statute.” Thereafter, Goyco filed an Appeal to the Appellate Division. On Appeal, the panel noted that N.J.S.A. 39:1-1 expressly defines a LSES as having “an electric motor that is capable of propelling the device with or without propulsion.” As Judge Hudak found, the definition of pedestrian under N.J.S.A. 30A:6-4 is incompatible with the definition of a LSES and, therefore, N.J.S.A. 39:4-14.16(g), by its terms, has no application here. The panel was also not persuaded that an LSES operator can be equated to a bicyclist, noting that the statute’s exception defeats this argument. They found that “[a]ll statutes . . . rules and regulations applicable to bicycles. . . shall apply to a LSES except those provisions which by their very nature may have no application to . . . a LSES.” As such, the Appellate panel affirmed the lower courts dismissal of the complaint. On October 6, 2023, The New Jersey Supreme Court granted Goyco’s petition for certification and has agreed to review this ruling and establish whether or not the operator of a low-speed electric scooter is a ‘pedestrian’ under N.J.S.A. 39:6A-2(h), and therefore entitled to PIP benefits. On May 14, 2024, the Supreme Court of New Jersey affirmed the Appellate Division decision. The Supreme Court unanimously rejected Mr. Goyco’s reliance on N.J.S.A. 39:4-14.16(g). The Court held that by its very definition the electronic scooter is a vehicle propelled by other than muscular power (battery-power) and designed primarily for use on highway. The Court affirmed that, “by their very nature,” a low-speed electronic scooter does not qualify for PIP benefits. Therefore, Mr. Goyco was not a “pedestrian” for PIP benefits afforded to bicyclists as per the definition in N.J.S.A. 39:6A-2(h). The Supreme Court declined to expand the definition of pedestrian without more explicit language in the statute. Additionally, the Supreme Court also found that the scooter was “designed primarily for use on highways, rails and tracks,” even though the device used by Mr. Goyco on November 22, 2021, could not go faster than 15.5 miles per hour. The Court noted that “highway” is defined broadly as any main route, free to the public, such as a public road. Following the Supreme Court’s ruling, if a motor vehicle accident involves a motorized scooter being operated in New Jersey, the occupant of that scooter is not a pedestrian and will not be entitled to PIP medical expense benefits. Gary has extensive experience in disputes involving Personal Injury Protection claims and bodily injury claims. He also handles matters as a member of the Fraud/Special Investigation Practice Group. Gary primarily deals with evaluating both medical provider fraud and intentional/staged losses. In this arena, Gary has significant experience conducting Examinations Under Oath as it relates to both specific claims and broader SIU investigations. SIU Spotlight, Issue 1, Vol. 1, July 2024 is prepared by Marshall Dennehey to provide information on recent legal developments of interest to our readers. This publication is not intended to provide legal advice for a specific situation or to create an attorney-client relationship. We would be pleased to provide such legal assistance as you require on these and other subjects when called upon. ATTORNEY ADVERTISING pursuant to New York RPC 7.1 Copyright © 2024 Marshall Dennehey, all rights reserved. No part of this publication may be reprinted without the express written permission of our firm. For reprints or inquiries, or if you wish to be removed from this mailing list, contact tamontemuro@mdwcg.com.