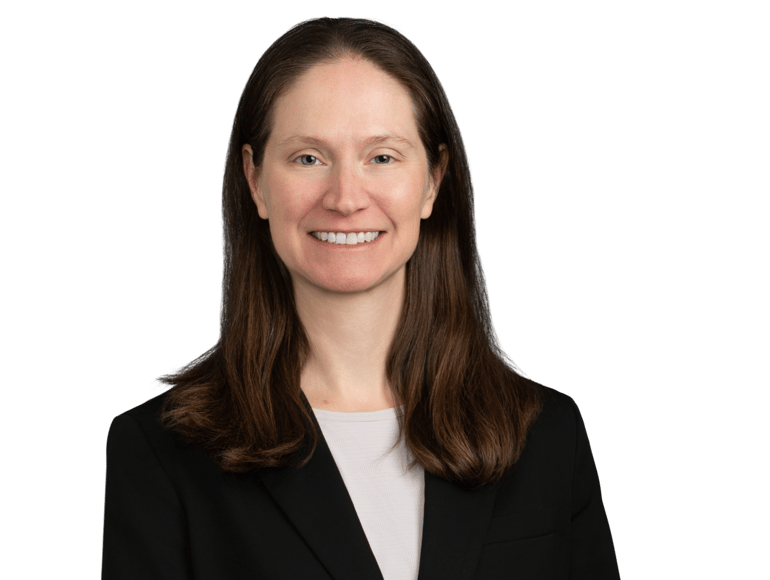
As a member of the firm's Professional Liability Department, Corey focuses her practice on representing and defending insurance companies in insurance coverage disputes and first-party property litigation.
Corey is a 2005 graduate of Florida Atlantic University where she received her bachelors' degree in History and Political Science. She received her juris doctor in 2011 from Nova Southeastern University's Shepard Broad Law Center. While in law school, Corey was a subscriptions and articles editor for the ILSA Journal for International and Comparative Law. She also interned at the Broward County Court Family Law division under Judge Melinda Kirsch-Brown.
Outside of the office, Corey is a passionate ultra marathon runner. In May 2019, she was the #1 overall female finisher and the second overall finisher in the Dunes 50 Miler, an off-road running race in Hobe Sound, Florida. The course includes hard-packed single track trails and several miles of rolling loose sugar sand dunes. Corey finished the 50-mile course in a little over 14 hours.
Results
Thought Leadership
Florida Supreme Court Rules Florida Statute §627.70152 Does not Apply Retroactively
October 26, 2026
In a decision that resolves years of appellate uncertainty and confirms that insurers and insureds alike can rely on the legal framework in place when a policy is issued, the Supreme Court of Florida last week found that Florida Statute §627.70152, which involves an insured’s requirement to provide an insurer with pre-suit notice before filing a suit, cannot be applied retroactively. In Universal Property & Casualty Insurance Company v. Hughes, the Court was presented with the issue of whether the statutory pre-suit notice requirement applied retroactively and whether it would apply to a breach of contract of an insurance policy that was issued before the statute went into effect. Before the Court was an appeal from a homeowner, Ms. Hughes, who sued her insurance carrier, Universal Property & Casualty Insurance Company (Universal) for breach of contract under an insurance policy that was in effect from April 24, 2019 through April 24, 2020. During the policy period, Ms. Hughes suffered a loss and, on May 29, 2019, made a claim for water damage. The carrier investigated the loss and issued payment; Ms. Hughes disputed the payment, finding the amount insufficient for repairs. On July 1, 2021, Florida Statute §627.70152 went into effect, which required insureds to provide notice of intent to initiate litigation against the carrier prior to filing a lawsuit; if an insured filed the lawsuit without complying with §627.70152, a court must dismiss the case without prejudice. On August 4, 2021, Ms. Hughes filed her lawsuit against Universal for breach of contract. Universal moved to dismiss based on her failure to comply with §627.70152. Ms. Hughes contended the notice requirement could not be applied retroactively. The trial court disagreed and dismissed the lawsuit without prejudice, and Ms. Hughes appealed. During the appeal, the Fourth District Court of Appeal, in Cole v. Universal Property & Casualty, 363 So. 3d 1089 (Fla. 4th DCA 2023), ruled that Florida Statute §627.70152 did apply retroactively to policies issued before the effective date of §627.70152. However, the Sixth District Court agreed with Ms. Hughes and overturned the trial court’s ruling, finding the statute could not retroactively apply to policies issued prior to the statute effective date. Thereafter, the other district courts weighed in, with the Third District Court agreeing with the Fourth District Court, and the First, Second and Fifth District Courts agreeing with the Sixth District Court. In resolving the conflict amongst the district courts, the Supreme Court advised “as a general rule, ‘the statute in effect at the time an insurance contract is executed governs substantive issues arising in connection with that contract.’ Hassen v. State Farm Mut. Auto. Ins. Co., 674 So. 2d 106, 108 (Fla. 1996). The Court applied the two-step test when deciding whether a statute has retroactive application: “First, the Court must ascertain whether the Legislature intended for the statute to apply retroactively. Second, if such an intent is clearly expressed, the Court must determine whether retroactive application would violate any constitutional principles.” Menendez v. Progressive Exp. Ins. Co., 35 So. 3d 873, 877 (Fla. 2010). In analyzing the Legislature’s intent, the Court must determine whether the Legislature has manifested a clear command for retroactivity in the statutory text. In review of the statutory text, the Court found nothing in the language of the statute to indicate that the phrase “all suits” was serving another purpose of expanding its reach to suits based on policies that both predate and postdate the enactment of the statute. Buis v. Universal Prop. & Cas. Ins. Co., 394 So. 3d 738, 741 (Fla. 2d DCA 2024). Further, the Court noted the statute has an effective date, which has long been considered to be evidence against retroactive application of a statute. The Court concluded that, on its face, no provision of §627.70152 speaks to application of the statute to insurance policies issued before the statute’s effective date and therefore, the Legislature did not clearly command retroactivity of the statute to include insurance policies issued prior to the enactment of the statute. The Court briefly reviewed Universal’s argument that the presuit notice requirement was procedural, not substantive, and therefore should be applied retroactively; however, the Court agreed with the Sixth District Court’s finding that, in its entirety, §627.70152 transformed an insured’s ability to sue an insurance company under a property insurance policy and an insurer’s obligations to respond to and pay insurance claims, thus making the requirement a substantive change. The Court thereby upheld the decision of the Sixth District and disapproved the decision of the Fourth District in Cole.
Legal Updates for Florida Coverage and Property Litigation
First DCA Reverses Excessive Jury Award Unsupported by the Evidence
October 5, 2026
In December 2019, the plaintiffs filed a claim with Universal for damages caused by a water and sewage back up through the plumbing system and existing through multiple fixtures including the washing machine drain, kitchen sink, dishwasher, bathtub and toilet. Universal investigated the claim, issued payment for resulting water damage totaling $7,000.00 in actual cash value ($12,000.00 in replacement cost value). The plaintiffs sought additional benefits for work needed to access the below-slab cast iron plumbing system due to the failure of the system from rust, deterioration, corrosion and breaks in the line. Universal denied any additional benefits for access. In 2021, the plaintiffs filed suit. During litigation, Universal sent a plumber to inspect the home and the plumber concluded the pipes were clogged but could be cleaned. The plaintiffs’ plumber testified that the plumbing system needed to be replaced due to holes and openings in the pipes. The plaintiffs introduced two estimates prepared by Triad Restoration services totaling $79,680.22 in replacement cost value and $50,219.97 in actual cash value and an executed contract with another company for repairs with the amounts of repair redacted. Since the insurance policy did not provide coverage for repair or replacement of the plumbing system, the jury only had to decide whether the plumbing system needed to be replaced, and if it did, Universal would owe for the access costs; the jury verdict form required the jury to determine both the replacement cost value and actual cash value amounts. The jury asked if it had to rely on the Triad estimates for their amounts. The trial court advised the amount awarded had to be based on the evidence presented at trial and the law given by the trial court. The jury awarded $335,000.00 in replacement cost value or $305,000.00 in actual cash value. Universal motioned for a new trial arguing the amount awarded was unsupported by the evidence and then moved for remittitur. The trial court denied both motions and this appeal followed. The court found that while a jury’s verdict should only be disturbed with caution and discretion, the trial court must give the properly challenged award close scrutiny and determine whether it bears a reasonable relation to the damaged provided, is supported by the evidence, and could have been reached in a logical manner by reasonable means §768.74(3), (5)(d)-(e), Fla. Stat. The court found the trial court did consider the statutory requirements at the hearing on Universal’s remittitur motion and was concerned about a reasonable relation to the amount of damages proved and injury suffered and whether the award was supported by the evidence, but ultimately denied the motion, reasoning that the jury had been properly instructed to fairly and adequately compensate the plaintiffs. The court noted the only evidence providing the basis for the jury verdict was Triad’s estimates and those valued the plaintiffs' claimed loss at $79,680.22 in replacement cost value and $50,219.97 in actual cash value; no valuation evidence reasonably supported the jury verdict. The plaintiffs argued that the jury was entitled to consider more than the estimates, but the court conveyed the evidence provided did not give the jury a way to reach the amounts they awarded. The court was also not swayed by the plaintiffs’ argument regarding inflation and later price increases, but the court noted that no evidence via the contract, nor testimony regarding increase in labor, material, fuel or construction costs were entered into the record. The court concluded the jury may draw reasonable inferences from the evidence, but it may not supply a damages number by speculation. The court did not find any of the plaintiffs’ remaining argument persuasive either. The court reversed the denial of Universal’s remittitur motion and motion for new trial as to damaged and remanded the case. The court ended its opinion with advising the trial court must determine whether replacement cost value or actual cash value is the property measure of damages under the policy and order remittitur in an amount consistent with that determination and the evidence.